

Vietnam’s Paper & Pulp Industry – Market Size & Growth Outlook
According to the report, the Vietnamese paper industry continues to record strong growth, with export turnover exceeding the 2.7 billion USD mark in 2024, maintaining a stable growth rate of 10-12% per year. It is forecasted that the paper packaging market in Vietnam will reach the 3.5 billion USD mark by 2026.
Meanwhile, Mordor Intelligence values Vietnam’s paper packaging market at USD 2.85 billion in 2025, with forecasts to grow to USD 4.54 billion by 2030, representing a strong CAGR of 9.73%. This figure highlights a clear shift in both businesses and consumers moving away from plastic towards sustainable paper solutions.
Across various market reports, there is strong consensus that demand for paper packaging in Vietnam is set for robust and long-term growth.
Vietnam’s Paper & Pulp Industry – Market Size & Growth Outlook
Vietnam’s Paper & Pulp Industry – Consumption Growth Driven by Domestic Demand
Consumption Growth Due to Paper Packaging
The rising consumption of paper packaging is attributed to several key factors:
- E-commerce & Retail: The explosive growth of e-commerce platforms and online shopping has significantly boosted demand for corrugated cartons and logistics packaging.
- Exports of Consumer Goods & Agro-Seafood Products: International trade requires high-quality packaging such as folding cartons and specialty paper to meet global export standards.
- Eco-Packaging Trends: Expanding into the EU and US markets requires compliance with strict environmental regulations, pushing businesses to switch from plastic to recycled, green, and sustainable paper packaging.
Domestic Demand in the Paper & Pulp Industry
A striking feature of Vietnam’s paper industry is its heavy reliance on imports. According to the General Department of Vietnam Customs (ASEMconnect, 2024), in just the first eight months of 2024, Vietnam imported 1.64 million tons of paper, with a total value of USD 1.45 billion, an increase of 17% in volume and 11.9% in value compared to the same period in 2023.
China remains the largest supplier, accounting for nearly 34% of total imports, followed by South Korea, Japan, and Indonesia. This highlights that domestic demand far outpaces local production capacity, forcing Vietnam to depend on global markets to secure supply. While this reliance opens up strong growth opportunities for local manufacturers and recyclers, it also creates challenges regarding cost pressures and supply chain stability.
Vietnam’s Paper & Pulp Industry – Consumption Growth Driven by Domestic Demand
Vietnam’s Paper & Pulp Industry – Key High-Growth Segments
Within Vietnam’s paper packaging industry, three segments are demonstrating the most dynamic growth:
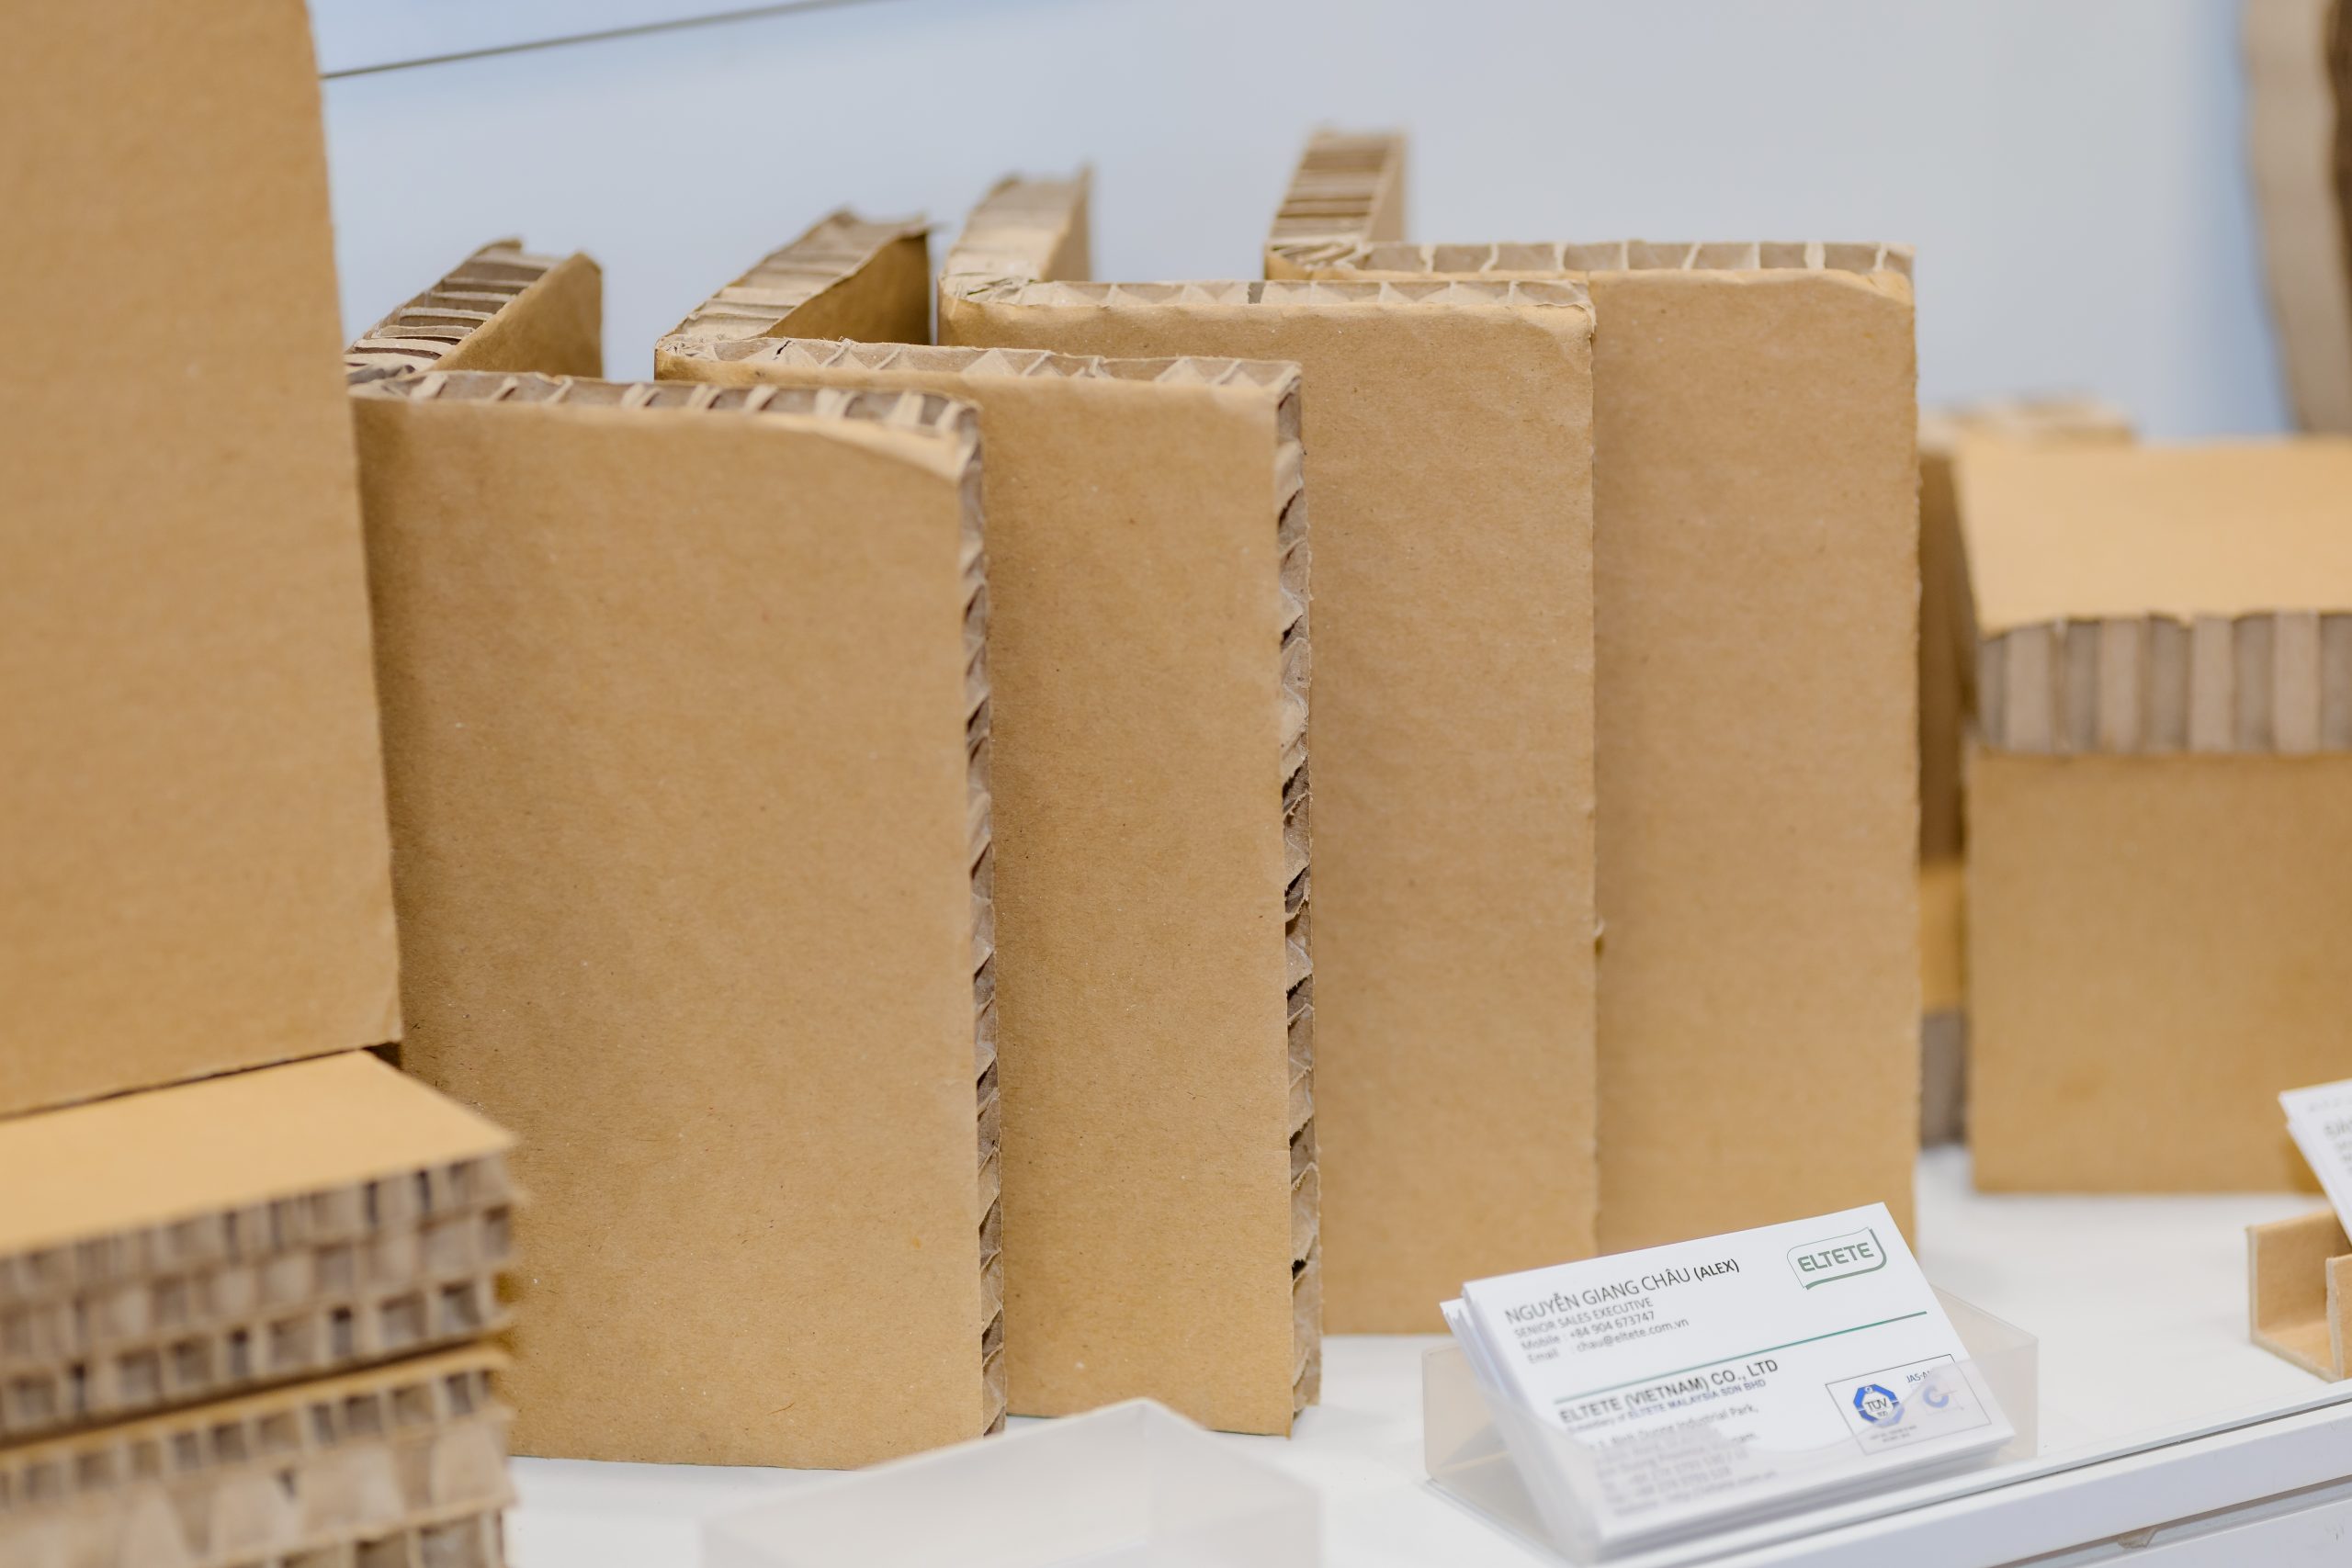
1/ Corrugated Boxes
This is the largest segment in both volume and consumption. With the expansion of e-commerce, logistics, and retail, demand for corrugated cartons remains strong. Market reports project continued stable growth, as corrugated packaging is indispensable in supply chains.
2/ Paperboard & Folding Cartons
Widely used in food, pharmaceuticals, cosmetics, and premium consumer goods, this segment is growing rapidly due to rising consumer expectations for high-quality products and strict export standards. It also allows Vietnamese manufacturers to move up the value chain and integrate deeper into the global supply network.
3/ Recycled Paper Packaging
This segment reflects the global sustainability shift. Many importing countries now enforce strict environmental regulations, compelling Vietnamese exporters to adopt recycled and eco-friendly packaging. However, limited domestic wastepaper supply and insufficient recycling capacity pose challenges. This requires stronger investment in recycling technology and infrastructure to meet future demand.
 Vietnam’s Paper & Pulp Industry – Key High-Growth Segments
Vietnam’s Paper & Pulp Industry – Risks & Challenges Impacting Domestic Consumption
Despite strong growth potential, Vietnam’s paper packaging industry faces several risks:
1/ Heavy Dependence on Imported Raw Materials
Reliance on imported pulp and recycled paper makes the market vulnerable to global price fluctuations and policy changes. Even minor adjustments in international trade regulations or freight costs can significantly impact local manufacturers.
2/ Rising Logistics & Operational Costs
Logistics costs remain a major challenge to competitiveness. Increases in fuel, electricity, and transportation expenses directly raise production costs, putting Vietnamese producers under pressure amid intense regional competition.

Vietnam’s Paper & Pulp Industry – Risks & Challenges Impacting Domestic Consumption
Paper Vietnam 2026 – Your Gateway to Solutions & Global Opportunities
At Paper Vietnam 2026, businesses will have the opportunity to access the latest advanced solutions to overcome these challenges. The exhibition also serves as a premier platform to connect with global suppliers, industry experts, and potential clients, while staying up to date with the newest market trends.
Register your booth: https://checkin.veas.com.vn/book-a-stand/PRC2027/forms/paper?locale=en